China
Sentiention
IntentionAttentionRetention
Entry
Feasibility & Structure
Entering China is a sequence, not a decision. Feasibility, regulatory mapping, entity, WFOE: structure follows the operating model, never the reverse. In the right order entry is cheap.
Backwards, it compounds.
Resolving rejected management allocation pools requires lodging a Mutual Agreement Procedure dossier with China State Taxation Administration within three years under Article 25 treaty rules.
Audit-resistant Chinese management charges require cost pools stripped of shareholder expenses and allocated via direct consumption drivers under Circular 16.
Chinese tax rules disallow EIT deductions for intra-group service fees failing the direct economic benefit test or covering shareholder management costs.
Foreign parent entities remain liable for retrospective corporate income tax and permanent establishment adjustments after China representative office cancellation.
Transitioning from deemed expense tax filings to a WFOE demands precise cut-off dates, contract novation, and tax clearance to avoid double taxation.
Representative offices face strict operational bans on direct revenue generation, employee hiring, and local invoicing while paying cost-plus deemed profit taxes.
Operation
Bridge & Ground
Operating in China is a daily discipline of language, cadence and presence. Distance is the real operating cost ~ a bridge on the ground turns intention into execution.
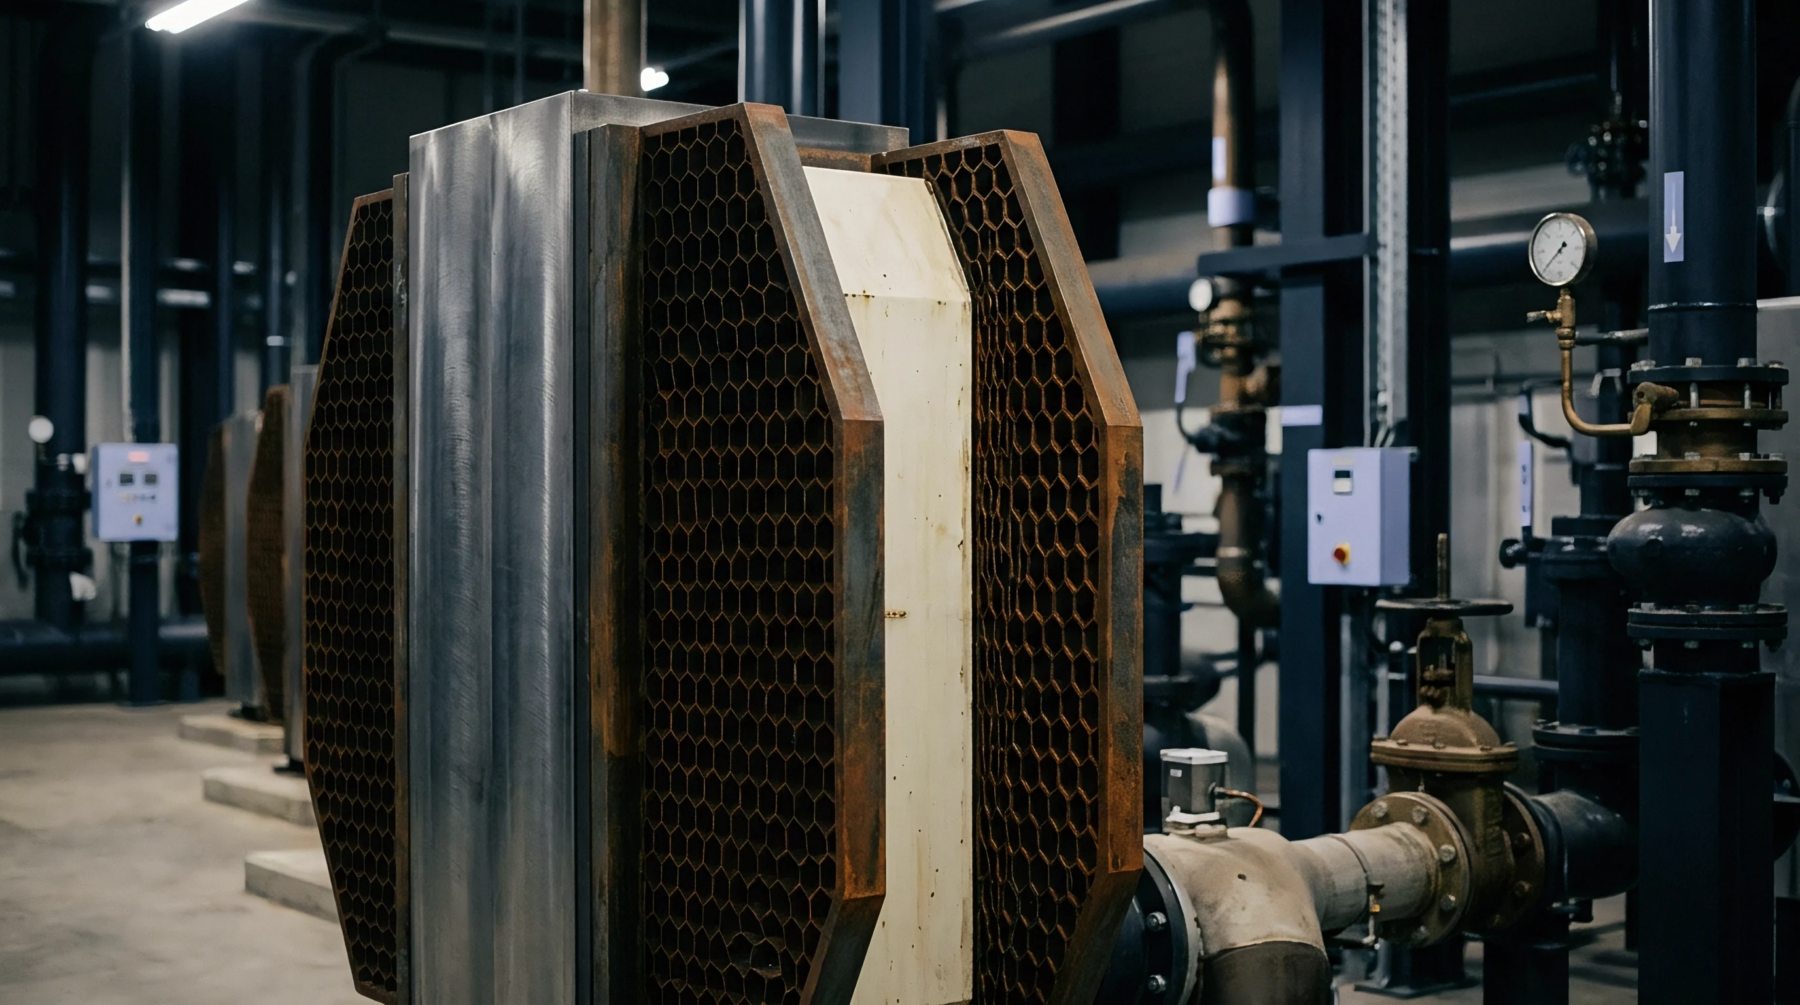
Thermal aging accelerates intermetallic layer growth and Kirkendall voiding, requiring substrate plating controls and aged shear testing to prevent brittle field failures.
Enforcing ENEPIG thickness windows per IPC-4556 eliminates galvanic hyper-corrosion, guaranteeing flip-chip solder joint integrity and wire bond reliability.
Pellet moisture gradients accelerate thermal hydrolytic chain scission in polymer melts, requiring radial drying verification to protect molecular weight.
Fickian diffusion and GAB isotherms govern package moisture ingress, requiring desiccant unit sizing matched to temperature-driven vapor pressure gradients.
Engineering plastics require strict moisture limits below 0.02% during melt processing to prevent irreversible hydrolysis, splay defects, and structural failure.
Contractual remedies require explicit regulatory indemnities, direct set-off rights against open payables, and unalterable batch tags to fully recover seizure losses.
Risk
Exposure & Exit
IP, dependency, enforcement, exit planning. China risk is managed by structure, not optimism, and every entry plan carries its exit plan. Exposure that is not written down is not managed.
Asset preservation under Chinese civil procedure freezes defendant liquidity and registry titles within 48 hours when supported by counter-guarantee insurance.
Resolve tax bureau valuation disputes by establishing commercial purpose under Public Notice 7 and settling pre-appeal security before challenging assessments.
Bulletin 7 requires buyers to withhold 10% tax on indirect transfers lacking commercial substance or face secondary penalties of 50% to 300% under Article 69.
PRC tax base for foreign equity transfers equals registered paid-in capital converted at historic injection FX rates, taxed at 10 percent on net RMB gain.
Unilateral Chinese indirect transfer taxes trigger non creditable double taxation unless managed through SPA holdbacks and bilateral MAP relief.
Notice Seven valuation apportionment requires splitting offshore transfer values between PRC taxable assets and non-PRC operations using auditable balance sheet metrics.